| Bottom | Home | Article | Bookshelf | Keyword | Author | Oxymoron |


Rare Earth Elements Battle

Cat: ECO
Pub: 2025/7
#2515b

GVS Deep Dive

25701u
Title

Rare Earth Elements Battle

レアアース元素を巡る闘争

Index
  1. Introduction:
  2. Rare Earth Elements Battle:
  3. Titanium Supply Chain:
  4. :
  1. 序文:
  2. 希少元素戦争:
  3. チタン金属サプライチェーン:
  4. :
Why?
   
Key
; ;
Title
Résumé
Ref

>Top 0. Introduction:

  • https://www.youtube.com/watch?v=sz9NbB4v58k
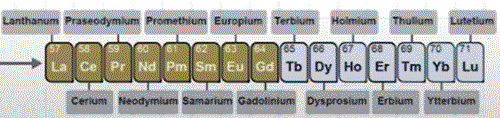
  • 57 La Lanthanum 镧lán; 58 Ce Cerium 铈shì;
    59 Pr Praseodymium 镨pǔ; 60 Nd Neodymium 钕nǚ;
    61 Pm Promethium 钷pǒ; 62 Sm Samarium 钐shàn;
    63 Eu Europium 铕yǒu; 64 Gd Gadolinium 钆gá;
    65 Tb Terbium 铽tè; 66 Dy Dysprosium 镝dí;
    67 Ho Holmium 钬huó; 68 Er Erbium 铒ěr;
    69 Tm Thulium 铥diū; 70 Yb Ytterbium 镱yì;
    71 Lu Lutetium 镥 lǔ
  • Rare-earth elements (REE), or called lanthanides, as well as scandium (Sc) and yttrium (Y), 17 minerals are usually called rare earths. Such minerals are applied in electronic componets, lasers, glass, magnetic materials, etc. 'Rare earths' are not actually scarce, but historically it took a long time to isolate these minerals.
    • Ce is 25th abundant element at 68 ppm more abundant than Cu, but they are spread thinly as trace impurities.
    • Sc and Y are considered rare earth elements because they occur in the same ore deposits, but have different electrical and magnetic properties.
    • These metals tarnish slowing in air to form hydrooxides liberating H, and react with steam to form oxides and ignite at 400ºC.
    • These elements and theri compounds have no biological function other thatn in several specialized enzymes. The water-soluble compounds are mildy toxic, but insolube ones are not.
    • Pr are radioactive and often found in minerals with Th and less commonly U.
    • Rare earth elements are typically dispersed and not ofter found concentrated in minerals.
    • The first rare-earth mineral discovered (1787) from a mine of Ytterby in Sweden, and four other rare-earth elements bear names derived from this location and Scandinavia. (Sm, Tb, Ho, Er, Yb, and Sc)
    • Minerals of rare-earth are mostly in bastnasite (RCO3F), monazite (XPO4) and loparite (Ce,Na,Ca)(Ti,Nb)O3) and lateritic clays.
    • Separation technisques were developed, such as ion exchange, fractional crystallization and liquid-liquid extraction since 1950s.
    • The classification or rare-earth elements: #57-61 light rare-earth element (LREE) and #62- heavey ones (HREE)


  • Abundance of Rare earth elements: vs. Si (希土類存在量)
  • Rare earth production: 希土類国別生産量


>Top 1.GVS Deep Dive (2025/6/22)

https://www.youtube.com/watch?v=sz9NbB4v58k (2025/6/22)

  1. Every time Israel is under attack, you hear about the Iron Dome. For us, it's a national security challenge because rare earths go into almost every form of defense technology from fighter jets and warships to missiles and tanks.
  2. (Caster) Welcome to GBS deep dive. I'm Neesh Minhas. When China imposed its rare earth export restrictions in April 2025, many in the West dismissed it as economic posturing*3 by the country. But as the conflict across Gaza, southern Lebanon, and now Iran deepens, Israeli weapon systems are beginning to falter*4 under sustained pressure of heavy usage. It's dawning*5 on many countries, although they still do not fully comprehend that this will be a calibrated geopolitical strike, should China wish it to be. One that doesn't require a single bullet. Welcome to the 21st century warfare when minerals and not missiles may determine who wins and who never fires at all. More details on this in a few minutes.
  3. But you may recall that earlier this month there was an uproar in the US as manufacturers, particularly automobile manufacturers, but also from other industries started thinking about closing down production lines because of a scarcity in the rare earth minerals. Magnet they needed, magnets they did not have. The rare earth materials became the key point in the second round of discussions between the US and China in the London talks. In fact, it was the Chinese dominance in those materials that actually got the US negotiators to come back quite literally with their tails between their legs*6. Not over tariffs, not over TikTok or chips, but over magnets. Post those talks, China has allowed limited, albeit*7 still tightly controlled, rare earth exports under strict licensing rules.
  4. According to the Wall Street Journal's analysis recently done of customs data in May 2025, China's rare earth magnet exports plunged*8 74% year on year with the shipments to the US down by 93%. And this is following the April licensing regime introduction. Now, this is the sharpest 1-month collapse in rare earth magnet exports since 2012 from China. The global supply chain didn't just bend, it basically snapped*9. The 1.2 million kg of rare earth magnets that are exported in May marked their lowest level since February 2020 during the Covid pandemic at the time. We know that the majority of the US imports of these rare earth materials comes from China. In fact, over 70% overall. However, in April 2025, when China updated its export control law, interestingly, in the context of today's topic, it explicitly banned rare earth minerals from being used or exported by military end use or to military end users unless granted special state level authorization. Chinese companies like JL MAG Rare earth and China Northern Rare Earth Group, which received export licenses recently from the country, are still effectively barred from selling to arms manufacturers or defense subcontractors unless the buyer demonstrates pure civilian use. It's not a gray zone. Beijing's licensing language is very precise. No material can be exported if its use in military applications cannot be excluded. This means defense giants like Lockheed Martin, Raphael, Northrup Grumman among others are out of bounds.
  5. Let's be clear, this wasn't a blanket ban. It was a precise cutting off raw rare earth exports specifically for military use. There's a critical distinction because virtually every modern weapons platform from the chips in missile guidance systems to the magnets in fighter jet engines all rely on these rare earth elements and most of those are either mined, refined, or dominated in processing by China. So for example briefly the US government's own research shows how tantalum (Ta) which is not a rare earth material as such but is another very critical material that's crucial for jet turbines in military aircraft is not mined in the US but most of its supply comes into the country after being refined in China. It's actually mined in Congo which has the largest tantalum mines but it gets labeled as a conflict material due to the origin and this is strict import laws both in the US and EU, and it isn't only the material that is crucial for the US.
  6. There are several rare earth materials including neodymium (Nd). dysprosium (Dy), and samarium (Sm) which can go into engines, sensors, radars from fighter jets, navy ships to submarines and so on. From smart bombs to stealth jets, every modern battlefield advantage runs through a supply chain that ends in China. This is clear US industrial fragility. As the US government accountability office has reported, domestic rare earth element refining is under 10% of all military demand. Missile production capacity is below 30% of what's needed in a sustained war. But no country is feeling the effects of this supply chain trans strangle*17 hold more acutely right now than Israel.
  7. Now coming to Israel. Israel's conflict with Iran is costing the country hundreds of millions of dollars a day according to the early estimates out. This is a high price tag even for the Israelis that will constrain its ability to conduct a lengthy war. And this is despite the fact that it receives over 3.3 billion dollars annually from the US through its foreign military financing program along with another 500 million dollars each year for cooperative missile defense systems as the Iron Dome, David Sling, and the Arrow Systems. So far in the last one and a half years, it's received over 23 billion dollars for emergency wartime aid since October the 7th attack by Hamas. According to one estimate, a war with Iran that lasts one month will cost Israel around 12 billion dollars militarily alone. And experts say that for Iran war, the biggest single cost are the interceptors that are needed to blow up incoming Iranian missiles, which alone can amount to between tens of millions of dollars a day to 200 million dollars a day.
  8. But then there is the rare earth that each one of those systems requires. Israel relies heavily on the US and domestic systems that require a steady supply of rare earth elements for its performance precision, and resilience in the battle. With China restricting military rare earth exports and Western stockpiles deleted by the Ukrainian war and for Israel in the ongoing Gaza conflict. Israel's now facing serious supply bottlenecks as it goes into this war with Iran. Israel's famous Iron Dome, which has so impressed Donald Trump that he said he now wants to build an equivalent one for the US called the Golden Dome. The Iron Dome batteries require radar systems built around high performance magnets. Each Tamil interceptor missile is estimated to cost between 40,000 to 100,000 dollars and it contains rare earth-based control systems that rely of neodymium (Nd) , praseodymium (Pr) , samarium (Sm), and cobalt magnets. Please excuse me when I say these names incorrectly. The number of them at the end are driving me crazy. Now, it's not just about the cost. It's about chemistry. Every single launch that Israel does drains Israel's own material supply of these reserves.
  9. Due to shortages, Israel has had to start rationing interceptor launches. It's prioritizing those missiles which have confirmed trajectory threats. This has increased the risk of saturation attacks getting through the Iron Dome, which is how Iran initially responded to the Israeli attacks last week. It sent over, let's say, 10 of those missiles aiming to get through the Iron Dome. If Israel had an 80% success rate of stopping them, 20% of them still got through. The David Sling*21 and AR3 are Israel's medium to long-range interceptors. The AR3 shields against the long range ballistic missiles that leave the Earth's atmosphere and they cost around 4 million dollars for every interception. It uses an infrared homing*23 system that depends on ytterbium (Yb) and it stabilized ceramics and a dysprosium (Dy) based magnets. Now these components are essential for target acquisition and heat shielding. The David Sling system, which was developed jointly by Israel and the US, can shoot down short to long range missiles, drones, and other aircraft. It costs around 700,000 dollars each time it's activated. And assuming it uses two interceptors, which is normally the minimum, launched, but you can't fire what you can't replace. The rare earths in their high temperature sensors and guidance optics without these key components like for example the thermal shielding and the killing of those vehicle sensors if that degrade or they can't be replaced.
  10. Unfortunately for Israel right now there is said to be a production delay at the Raphael advanced defense systems which is reportedly facing procurement delays because as we know even the European countries are facing delays from China in receiving those rare earths. The result is that missiles defense coverage gaps are growing especially as the pace of those incoming Iranian strikes increases. Then coming to the mighty fight F-35 fighter jets, Israel has around 42 of them. Each one of these contains over 400 kg of rare earths. Neodymium (Nd) and samarium (Sm) for motors, cerium (Ce) for display, gadolinium (Gd) for stealth coatings, ytterbium (Yb) in the ceramic heat shields and so on and so forth*27. Without these all the repair cycles break down and the fighter's readiness obviously suffers. Now, these jets require high precision spare parts, and they're often sourced via the US and the EU supply chains that depend on Chinese processed rare earths, which as we now know are short supply to these countries. Maintenance is delayed. Fewer jets are mission ready at any given time. Training flights are said to have been reduced to preserve any component life cycles.
  11. Now, all of this has been highlighted after a leaked Knesset*28 briefing document which estimated that Israel could run out of key interceptors within 10 to 14 days. With the US missile replenishment*29 also being limited, we are actually seeing a massive impact due to these raw material shortages on military equipment. Brings us to an interesting rare moment. Let's speculate for a moment. Peace by depletion. Now, if Western nations cannot manufacture those missiles or their jets and they cannot fight, China then didn't end the war with soldiers. It did it with supply chain leverage. Share with me your thoughts on this. Have a great day.


  1. イスラエルが攻撃を受けるたびに、Iron Domeの話題が聞くことでしょう。希土類は戦闘機や軍艦からミサイルや戦車まで、あらゆる防衛技術に使用されているため、これは国家安全保障上の課題です。
  2. <News caster> GBS Deep Dive番組へようこそ。Neesh Minhasです。2025/4/に中国が希土類輸出制限を課した際、西側諸国の多くはこれを中国の経済制裁だと見なしました。しかし、ガザ地区、南レバノン、そして今やイランを巡る紛争が深刻化するにつれ、イスラエルの兵器システムは継続的な大量使用による圧力に弱体化し始めています。多くの国々が、これが中国が望むならば、綿密に計画された地政学的攻撃となることをまだ完全には理解していないものの、弾丸を一切必要としない攻撃となることを、ようやく理解し始めています。ミサイルではなく全く発砲しない鉱物資源が勝敗を分ける21世紀の戦争の形です。これについては、後ほど詳しく説明します。
  3. しかし、今月(2025/6)初めに米国で大騒動があったことを覚えているかもしれません。製造業、特に自動車メーカーだけでなく他の産業も、希土類鉱物の不足により生産ラインの閉鎖を検討し始めています。必要な磁石がなかったのです。希土類材料は、ロンドン会談における米国と中国の第2ラウンドの協議の重要なポイントとなりました。実際、これらの材料における中国の優位性こそが、米国の交渉担当者が文字通り尻尾を巻いて戻ってくる原因となったのです。関税問題でも、TikTokやチップの問題でもなく、磁石のせいだったのです。これらの会談後、中国は厳格なライセンス規則の下で、限定的ですが、依然として厳しく管理されている希土類の輸出を許可しました。
  4. Wall Stree Journalが最近行った2025/5月/の通関データの分析によると、中国の希土類磁石輸出量は前年比74%減、米国向けは93%減となった。これは4月の輸出許可制度導入後のことです。これは、2012年以来、中国からの希土類磁石輸出量の1ヶ月間の急激な落ち込みとなりました。世界のサプライチェーンは単に歪んだだけでなく、事実上、断線したのです。5月に輸出された120万kgの希土類磁石は、新型コロナウイルス感染症のパンデミックが続いた2020/2/以来の最低水準を記録しました。米国が輸入するこれらの希土類材料の大部分は中国から来ています。実際、全体の70%以上が中国から来ています。興味深いことには、2025/4月/に中国が輸出管理法を改正した際、.この話題に関連して、国家レベルの特別な許可がない限り、軍事目的での使用または軍事エンドユーザーへの希土類鉱物の使用または輸出が明らかに禁止されました。中国から最近輸出許可を取得したJL MAGレアアースや中国北方希土集団などの中国企業は、購入者が純粋な民生用途を証明しない限り、依然として武器メーカーや防衛関連の下請企業への販売を事実上禁じられています。これはグレーゾーンではありません。北京のライセンス規定は非常に明確です。軍事用途への使用を排除できない限り、いかなる物質も輸出できません。即ち、Lockheed Martin、Raphael、Northrup Grumman といった防衛産業大手は輸出対象外なのです。
  5. 明確なのは、これは全面禁止措置ではなく、軍事用途に特化したレアアース原料の輸出を厳密に停止した措置だということです。ミサイル誘導システムのチップから戦闘機エンジンの磁石に至るまで、事実上あらゆる現代兵器の基盤はこれらの希土類元素に依存しており、そのほとんどは中国で採掘・精製・加工されているからです。例えば、米国政府自身の調査によると、厳密には希土類ではありませんが、軍用機のジェットタービンに不可欠な非常に重要な材料であるタンタル (Ta)は、米国では採掘されておらず、その供給の大部分は中国で精製された後に米国に輸入されていることが明らかになっています。実際には、タンタル鉱山が世界最大規模を誇るコンゴで採掘されていますが、その産地から紛争鉱物と指定されており、米国とEUの厳格な輸入規制を受けています。さらに米国にとって重要材料はタンタルだけではありません。
  6. ネオジム (Nd)、ジスプロシウム(Dy)、サマリウム(Sm)などは、戦闘機、艦艇、潜水艦などのエンジン、センサー、レーダーなどに利用できる希土類元素は数多く存在します。スマート爆弾からステルス機まで、現代の戦場におけるあらゆる優位性は、中国に端を発するサプライチェーンによって支えられています。これは米国の産業の脆弱性を如実に示しています。米国会計検査院の報告によると、国内の希土類元素精製は軍事需要全体の10%にも満たず、ミサイル生産能力は持続的な戦争に必要な量の30%にも満たないのが現状です。しかし、このサプライチェーンの窒息状態の影響を、現在のイスラエルほど深刻に感じている国はありません。
  7. イスラエルについてですが、初期の推計によると、イスラエルとイランの紛争は、同国に1日あたり数億ドルの費用をかかっています。これはイスラエルにとっても高額であり、長期戦を遂行する能力を制約することになります。しかも、イスラエルは対外軍事援助プログラムを通じて米国から年間33億ドル以上を受け取っているにもかかわらず、Iron Dome、David Sling、Arrow Systemsといったミサイル防衛システムにも毎年5億ドルの援助を受けています。過去1年半だけでも、10/7のハマスによる攻撃以降、緊急戦時援助として230億ドル以上を受け取っています。ある推計によると、1か月続くイランとの戦争は、イスラエルに軍事費だけで約120億ドルの費用がかかるとされています。専門家によると、イランとの戦争で最も大きな費用は、イランのミサイルを迎撃するために必要な迎撃ミサイルで、これだけでも1日あたり数千万ドルから2億ドルに上ると見込まれています。
  8. しかし、これらのシステム各々に必要な希土類元素があります。イスラエルは、戦闘における性能精度と耐久性を確保するために、米国および国内のシステムに大きく依存しています。中国が、軍事用希土類元素の輸出を制限し、ウクライナ戦争と進行中のガザ紛争でイスラエルが保有する西側諸国の備蓄が減少する中、イスラエルは現在、イランとの戦争に突入するに当たり、深刻な原材料供給ボトルネックに直面しています。イスラエルの有名なIron Domeは、Trump大統領に強い感銘を与え、米国にもGolden Domeと呼ばれる同様のものを建設したいと発言しています。Iron Domeのバッテリーには、高性能磁石を基盤としたレーダーシステムが必要です。Tamilの迎撃ミサイル1発の価格は4万ドルから10万ドルと推定されており、ネオジム (Nd)、プラセオジム(Pr)、サマリウム(Sm)、コバルト磁石を用いた希土類ベースの制御システムが搭載されています。これら元素の名称を誤って発音した場合はご容赦ください。難しくて気が狂いそうです。問題はコストだけではありません。化学反応の問題です。イスラエルが行う打ち上げは、イスラエル自身の物質的備蓄を枯渇させています。
  9. 中国による希土類元素磁石の輸出:
    物資不足のため、イスラエルは迎撃ミサイルの発射を制限せざるを得なくなりました。軌道上の脅威が確認されたミサイルだけを優先的に迎撃するようになったのです。これにより、Iron Domeを貫通する攻撃のリスクが高まりました。これは、イランが先週イスラエルの攻撃に当初行った対応と似ています。イランはIron Domeを貫通することを目的として、例えば10発のミサイルを発射しました。イスラエルの阻止率が80%だったとしても、20%は貫通しました。イスラエルの中長距離迎撃ミサイルは、Dvud SkubgとAR3です。AR3は大気圏を離脱する長距離弾道ミサイルを迎撃するもので、迎撃1回あたり約400万ドルの費用がかかります。イッテルビウム(Yb)と安定化セラミック、そしてジスプロシウム(Dy)ベースの磁石を用いた赤外線ホーミング・システムを採用しています。現在、これらの部品は目標捕捉と熱遮蔽に不可欠なものとなっています。イスラエルと米国が共同開発したDvid Sling Systemは、短距離から長距離のミサイル、ドローン、その他の航空機を撃墜できます。迎撃1回あたり約70万ドルの費用がかかります。通常は最小限の2基の迎撃ミサイルを発射すると想定しますが、交換できないものを発射することはできません。高温センサーや誘導光学系に使用されている希土類元素は、例えば熱シールドのような重要部品がなければ機能しません。また、車両センサーが劣化したり交換できない場合は機能しなくなります。
  10. イスラエルにとって残念なことは、現在、Raphael先進防衛システムの生産に遅れが生じていると言われており、報道によると調達の遅れが生じています。これは、周知のとおり、欧州諸国でさえ、中国からの希土類元素の受領に遅れが生じているためです。その結果、特にイランによる攻撃のペースが早まるにつれて、ミサイル防衛の成功率のギャップが拡大しています。次に、強力な戦闘機F-35について言えば、イスラエルは約42機保有しています。これらは1機あたり400kg以上の希土類元素を含んでいます。モーター用のネオジム(Nd)とサマリウム(Sm)、ディスプレイ用のセリウム(Ce)、ステルスコーティング用のガドリニウム(Gd)、セラミックヒートシールドのイッテルビウム(Yb)などです。これらがなければ、修理サイクルがすべて崩壊し、戦闘機の即応性は明らかに低下します。これらのジェット機には高精度の部品が必要であり、それらは多くの場合、中国産の希土類元素に依存する米国やEUのサプライチェーンを通じて調達されています。しかし、これらの国々ではレアアースの供給が不足していることは周知の事実です。メンテナンスは遅延し、任務遂行可能なジェット機の数は減少しています。部品のライフサイクルを維持するために、訓練飛行も削減されたと言われています。
  11. これら全ては、イスラエルの主要な迎撃ミサイルが10日から14日以内に枯渇する可能性があると推定したクネセト(議会)のブリーフィング文書が流出したことで、浮き彫りになりました。米国のミサイル供給も制限されているため、軍事装備における原材料不足による甚大な影響が出ています。これは、非常に興味深い珍しい状況です。少し推測してみましょう。いわば材料の枯渇による平和です。さて、西側諸国がミサイルやジェット機を製造できず、戦闘もできないのであれば、中国は兵士を使って戦争を終わらせたのではなく、サプライチェーンの力で終わらせたのです。これについて、あなたの考えをお聞かせください。ではまた。
  1. a
  2. a
  3. posture: 姿勢を取る, ふるまう
  4. falter: ためらう
  5. dawn: わかり始める


  6. with their tails between their legs: 尻尾を巻いて, しょげかえって


  7. albeit |ɔːlbíːit|: although
  8. plunge: 落ち込む <plumbum =Pb


  9. snap: 折れる


  10. a
  11. a


  12. tantalium =tantal: #73元素, Ta
  13. a


  14. a
  15. a


  16. strangle: 絞殺, 窒息
  17. a


  18. a


  19. a


  20. sling: 石投げ器
  21. a


  22. home: 自動装置で誘導する
  23. a
  24. a


  25. a


  26. and so on and so forth: その他諸々


  27. Knesset: Israelの国会
  28. replenish: 補充する

>Top 2. Titinium Supply Chain:

https://www.youtube.com/watch?v=iKDsZOzISI8

  1. Supply chain disruption, titanium (Ti)*3 shortage, production halted, Why China is preparing to tighten its grip on one of the most critical materials in modern industry, Ti. If Beijing moves forward with a full-scale export ban, it could cripple Western industries, bringing aerospace, defense, and most dangerously, the robotic sector to a grinding halt. Right now, Ti is a cornerstone of high-tech manufacturing used in everything from fighter jets to surgical implants. But Western reliance on China for this resource has put entire industries in a dangerous chokehold*4. Beijing has already weaponized its control over rare earth minerals, cutting off supplies to the West as a countermeasure to trade restrictions. If Ti follows, the consequences will be far worse. How bad could it get? Let's break it down.
  2. But first, if Ti vanishes from Western supply chains, which industries collapse first? Keep watching. Ti isn't just another metal. It's stronger than steel (per unit weight), (but not) lighter than aluminum, and resistant to corrosion. That's why it's an irreplaceable*6 component in some of the most advanced technologies in the world. Defense; the F35 fighter jet, already a financial black hole for the Pentagon, relies on hundreds of Ti components. The US Navy's submarines, Ti holes*7, spacecraft, missiles, body armor. Cutting off Ti would paralyze Western military manufacturing. Robotics; here's the problem. Ti is the skeleton*8 of high-end industrial robots. Without it, companies like Boston Dynamics*9, Tesla, and ABB*10 would face crippling delays and skyrocketing costs. The dream of reshoring*11 Western manufacturing, bringing factories back home with automated workforces, collapses overnight. But is this just a hypothetical scenario? Or is China already laying the groundwork for a ban? That's where things get even more interesting.
  3. Automation is supposed to be the West's solution to labor shortages and rising wages. But there's a catch. Without Ti, building industrial robots becomes a logistical nightmare. A single robotic arm used in automobile assembly lines requires high strength, lightweight materials, and Ti is the best option. If China shuts off exports, the West faces a crisis on two fronts. No Ti means no robots. No robots mean no future for domestic manufacturing. Can't we just use steel or aluminum instead? Theoretically, yes. But switching materials comes with serious trade-offs. Steel is heavier. It slows down robots and increases energy consumption. Aluminum is weaker. It fails under high stress. So, is the West trapped or are there alternative sources? Let's take a hard look at where Ti really comes from.
  4. The global Ti supply chain is a geopolitical minefield. China, Russia, and Kazakhstan together control an estimated 65% of global Ti production. According to the latest figures from the International Ti Association, China alone accounts for 35% with Russia supplying 25% and Kazakhstan adding another 5%. These countries dominate not only raw material extraction, but also the high-grade Ti processing required for aerospace, robotics, and military applications. Beijing's Biotio Group*14, the world's largest Ti producer, supplies an overwhelming share of Ti sponge, a critical raw form of the metal exported to Western nations. The US, in contrast, produces less than 5% of the global supply and remains entirely dependent on imports with the Pentagon alone sourcing 85% of its Ti needs from foreign suppliers. The looming*14 question, if China enacts a ban, where does the West turn? The options are scarce and each comes with steep costs or geopolitical entanglements that make a quick pivot nearly impossible.
  5. Japan's Ti industry, led by Toho Ti (東邦チタン) and Osaka Ti (大阪チタニウムテクノロジーズ) Technologies (), is among the most adv advanced globally, producing roughly 15% of the world's high purity Ti sponge, while Japan is a leader in Ti processing, it still depends on China and Russia for a significant portion of its raw materials, creating a supply bottleneck that Western batuibs cabbit sunokt bypass. According to the Japan Ti Society, Japan's production output has remained relatively stable at around 40,000 MT annually compared to China's 210,000 MT. A shift to Japanese supply would cause price surges of up to 40% making Ti intensive industries like aerospace and robotics financially unsustainable. Moreover, Japan's firms are deeply integrated into the Chinese supply chain. Meaning that if Beijing cuts exports, Japanese suppliers could also face disruptions either due to shortages or indirect pressure from Chinese regulators. In essence, Japan isn't a replacement, It's another vulnerable link in the Ti crisis.
  6. Mozambique, South Africa, and Kenya hold some of the world's largest untapped Ti reserves, particularly in the form of ilmentie*17 ore, a primary Ti source. However, these regions offer no real escape from China's dominance, as Beijing has spent the last decade securing exclusive mining rights across Africa through Belt and Road Initiative investments. Chinese firms including China National Nuclear Corporation (CNNC), and Loman Billions Group, now operate over 70% of Mozambique's Ti mining pr9ojects, according to African Business Magazine. The MoMA Ti mine*19, Africa's largest, exports nearly 90$ of its output to China, which is then refined and processed into aerospace grade Ti.
  7. Western companies like Tronox Holdings and Kenmare Resources have operations in these regions, but their output is insufficient to offset a Chinese export ban. Effectively, even if the West shifts supply chains to Africa, China's control over refining capacity ensures that raw Ti remains locked within Beijing's sphere of influence. Ti's unique combination of strength, lightweight properties, and corrosion resistance makes it irreplaceable in robotic manufacturing, particularly for high performance industrial robots. Al-driven automation and surgical robotic arms.
  8. Alternative materials like steel and aluminum pose serious drawbacks*21. Steel is too heavy, reducing energy efficiency and speed, while aluminum lacks the required durability, leading to increased maintenance cost. Carbon fiber composts*20 have been explored, but they lack Ti's heat resistance and are significantly more expensive to produce at scale. According to the International Federation of Robotics, global industrial robot sales hit 553,000 units in 2023, a 5% increase year-over-year, with China leading the market at 52% of total installations. A Ti ban would Western automation ambitions, driving up production costs and forcing manufacturers to redesign entire robotic architectures, an effort that could take years and cost billions in R&D. At present, there is no viable substitute that maintains both the cost effectiveness and performance of Ti, making China's potential export restriction a direct threat to the future of Western automation.
  9. China has long pursued vertical integration in the robotic supply chain, controlling everything from rare earth minerals to semiconductor production. Ti is the final missing piece in Beijing's technological dominance strategy. The made in China 2025 plan, which aims to make China the global leader in AI, robotics, and industrial automation, has already funneled*22 over 150 billion dollars into domestic manufacturing subsidies. According to China's Ministry of Industry and Information Technology, Chinese companies including CS Robot and Automation and DJI are aggressively expanding robotics production capacity with plans to quadruple output by 2030 by restricting Ti exports. China doesn't just weaken Western competitors. It forces foreign robotics firms to establish production facilities in China, effectively transferring intellectual property and technology leadership to Beijing. The West's dependence on Chinese robotics exports has already reached a critical threshold with companies like ABB, Cuka, and Yasco increasingly integrating China manufactured components into their systems. If China pulls the trigger on a Ti ban, it won't just disrupt supply chains. It will dictate the future of the robotics industry itself.
  10. Despite Western sanctions on Russian Ti, companies like Airbus, Bowing, and Rolls-Royce continue quietly securing supply through third-party nations, particularly via India, Turkey, and the UAE. Russian Ti giant VSMPO Avisma, which supplies one-third of global aerospace grade Ti, has found workarounds*24 through re-export agreements, effectively sidest*26 stepping sanctions. Airbus CEO Guom Fry has openly lobbied the EU against expanding Ti restrictions, warning that cutting off Russian Ti could lead to a production crisis worse than the chip shortage. The aerospace industry's dependency on Ti is so severe that Boeing, after initially halting Russian Ti purchases in 2022, has reportedly sought alternative routes through Southeast Asian intermediaries*27, according to Reuters. The reality is simple. Western aerospace giants cannot afford to abandon Russian Ti, making China's potential ban even more dangerous. Because if both Moscow and Beijing cut exports, there is no alternative supply large enough to prevent an indusry-wide collapse.
  11. Recycling Ti is technically possible but economically impractical at scale. Unlike aluminum or steel, Ti requires high purity processing, and only 5% of Ti scrap is currently recycles globally. According to the Ti Metals Corporation, the US and Europe lack the infrastructure to process recycled Ti in meaningful quantities with only a handful of facilities capable of refining aerospace grade material. The Pentagon has pushed for increased Ti stockpiling, but current reserves would only 12 to 18 months in a crisis scenario, far below what's needed for long-term supply stability. A strategic shift towards stockpiling should have started years ago. But now with a potential Chinese export ban looming, industry leaders fear that the window for preparation has already closed. Aerospace and defense will bear the brunt*28 of a Ti crisis.
  12. With aviation facing crippling delays and cost surges, Airbus and Boeing, the two largest commercial aircraft manufacturers, source over 50% of their Ti from China and Russia, according to industry estimates. Boeing's 787 Dreamliner alone contains over 14 MT of Ti used in airframes, landing gear, and critical engine components. Any disruption in supply could add billions in extra costs and stall*29 production timelines by up to 5 years. Based on projections from the European Aerospace Industry Association, defense contractors are equally vulnerable. Lockheed Martin's F35 fighter jet, a cornerstone*31 of US air superiority, is composed of 40% Ti by weight. Pentagon insiders warned that without a stable supply, jet production could drop by 30% within 2 years, significantly weakening NATO's long-term military capabilities. The US Department of Defense currently imports 85% of its Ti, making it highly exposed to any strategic export bans from Beijing or Moscow.
  13. While construction also relies on Ti, particularly in high performance alloys for bridges, skyscrapers, and industrial equipment, the impact will be less catastrophic. The Global Construction Review reports that shifting to alternatives like high strength steel or aluminum could increase materiel costs by 20 to 30%, forcing developers to either absorb higher expenses or delay projects altogether. However, in sectors like nuclear power plant construction, where Ti is used in corrosion resistant piping and cooling systems, finding substitutes will be far more complex. Annalist from Wood Mckenzie caution that a prolonged supply crunch could increase global infrastructure costs by 10 billion dollars annually.
  14. Though the most immediate threat remains in aviation and defense, where Ti is simply irreplaceable. The West faces a now or never moment to secure its Ti supply chain, but options are limited and costly. Washington is already exploring domestic mining projects in Utah and Colorado, but regulatory hurdles and environmental concerns mean it could take over a decade to develop these reserves. EU is scrambling*33 to secure Ti trade agreements with India and Brazil, but these efforts remain largely in early stages. At this point, strategic alliances with Japan and Australia remain the most realistic short-term solutions, though they fail to fully offset a Chinese ban. Meanwhile, China is tightening its grip. And if Beijing enforces export controls, Western industries will be caught in a supply chain crisis with no quick fix*34.
  15. Ti isn't just a commodity. It's a power play in the fight for technological and industrial dominance. The West is running out of options and unless urgent action is taken, China will dictate the future of robotics, aerospace, and defense. We're glad you're enjoying this video.

2.

  1. サプライチェーンの混乱、チタン (Ti)の不足、生産停止があります。中国が現代産業において最も重要な素材の一つであるTiの統制強化を準備している理由です。北京が全面的な輸出禁止に踏み切れば、西側諸国の産業は麻痺状態に陥り、航空宇宙、防衛、そして最も危険なことにがロボット産業が停止に追い込まれる可能性があります。現在、Tiは戦闘機から外科用インプラントまで、あらゆるものに使われるハイテク製造業の要となっています。しかし、西側諸国がこの資源を中国に依存していることで、産業全体が危険な締め付け状態に陥っています。北京はすでに希土類鉱物資源の支配を武器化し、貿易制限への対抗策として西側諸国への供給を遮断しています。Tiも同様の措置を取れば、事態はさらに悪化することになります。それはどれほど悪化もたらすのか、詳しく見ていきましょう。
  2. しかしまず、もしチタンが欧米のサプライチェーンから消えたら、どの産業が最初に崩壊するのでしょうか?今後の動向に注目してみて下さい。チタンは単なる金属ではありません。単位重量あたりでは鋼鉄よりも強度が高く、アルミニウムよりは軽くはないものの、耐腐食性があります。だからこそ、世界で最も先進的な技術において、チタンは欠かせない材料なのです。防衛分野では、既にペンタゴンの財政的ブラックホールとなっているF35戦闘機は、数百ものチタン製の部品に依存しています。米海軍の潜水艦、チタンホール、宇宙船、ミサイル、防弾チョッキなどにもチタンが使われています。チタンが途絶えれば、欧米の軍事産業やロボット産業は麻痺してしまいます。問題はそこにあります。チタンは高性能産業用ロボットの骨格です。チタンがなければ、ボストン・ダイナミクス、テスラ、ABBなどの企業は、深刻な遅延とコスト高に直面することになります。欧米の製造業を呼び戻し、自動化された労働力を備えた工場を国内に戻すという夢は、一夜にして崩れ去ってしまうのです。しかし、これは単なる仮説のシナリオなのでしょうか?それとも中国はすでに禁止に向けて準備を進めているのでしょうか? これから事態はさらに懸念材料になります。
  3. 自動化については、労働力不足と賃金高騰に対する西側諸国の解決策であります。しかし、落とし穴があります。Tiがなければ、産業用ロボットの製造は物流上の悪夢となります。自動車組立ラインで使用されるロボットアームには、高強度で軽量な材料が必要であり、Tiが最適な選択肢なのです。中国が輸出を停止した場合、西側諸国は2つの面で危機に直面することになります。Tiがなければロボットも存在しませんし、ロボットがなければ、国内製造業の未来はありません。代わりに鉄鋼やアルミニウムを使用できないでしょうか?理論上は可能です。しかし、材料の切り替えには深刻なトレードオフが伴います。鉄鋼は重いのです。ロボットの速度が低下し、エネルギー消費が増加します。アルミニウムは強度が低く、高圧力で破損します。では、西側諸国は窮地に陥っているのでしょうか、それとも代替供給源があるのでしょうか?Tiが実際には供給源を含めて、詳しく見ていきましょう。
  4. 世界のチタンサプライチェーンは地政学的な地雷原のようです。中国、ロシア、カザフスタンの3カ国で、世界のチタン生産量の約65%を占めていると推定されています。国際チタン協会 (ITA)の最新データによると、中国だけで35%、ロシアが25%、カザフスタンが5%を供給しています。これらの国々は、原材料の採掘だけでなく、航空宇宙、ロボット工学、軍事用途に必要な高品質のチタン加工も担っています。世界最大のチタン生産者である北京のBioteグループは、西側諸国に輸出される重要なチタン原料であるスポンジチタンの圧倒的なシェアをもっています。一方、米国のチタン生産量は世界全体の5%未満で、依然として完全に輸入に依存しており、国防総省だけでも必要なチタンの85%を海外のサプライヤーから調達しています。差し迫った問題は、中国が禁止措置を発動した場合、西側諸国はどこへ向かうのかということです。選択肢は少なく、それぞれに高額なコストや地政学的な問題が伴い、迅速な方向転換はほぼ不可能です。
  5. 東邦チタンと大阪チタニウムテクノロジーズが率いる日本のチタン産業は、世界でも最も先進的な産業の一つであり、世界の高純度チタンスポンジの約15%を生産しています。日本はチタン加工のリーダーである一方で、原材料のかなりの部分を中国とロシアに依存しており、西側諸国が回避できない供給のボトルネックとなっています。日本チタン協会によると、日本の生産量は年間約4万トンで比較的安定しているのに対し、中国は21万トンです。供給元を日本にシフトすれば、最大40%の価格高騰を引き起こし、航空宇宙やロボット工学などのチタン集約型産業は財政的に持続不可能になります。さらに、日本企業は中国のサプライチェーンに深く組み込まれています。つまり、北京が輸出を削減した場合、日本のサプライヤーも数量不足や中国規制当局からの間接的な圧力により混乱に直面する可能性があります。本質的に、日本は代替ではなく、TI危機におけるもう一つの脆弱なリンクです。
  6. モザンビーク、南アフリカ、ケニアは、世界最大級の未開発チタン埋蔵量を有しており、特にチタンの主要資源であるイルメナイト鉱石の形でその埋蔵量が多いです。しかし、これらの地域は中国の支配から逃れる手段とはなり得ません。中国政府は過去10年間、一帯一路構想への投資を通じて、アフリカ全土で独占的な採掘権を確保してきました。アフリカン・ビジネス・マガジンによると、中国核工業集団 (CNNC) やLoman Billions グループなどの中国企業が、現在、モザンビークのチタン採掘プロジェクトの70%以上を操業しています。アフリカ最大のモザンビークのMomaチタン鉱山は、採掘量の約90%を中国に輸出しており、そこで精錬・加工されて航空宇宙グレードのチタンに加工されています。
  7. Tronox HoldingsやKenmare Resourcesといった欧米企業もこれらの地域で操業していますが、その生産量は中国の輸出禁止措置を相殺するには不十分です。事実、西側諸国がサプライチェーンをアフリカに移転したとしても、中国が精錬能力を掌握しているため、原料チタンは北京の影響圏内に留まることになります。チタンは強度、軽量性、耐腐食性という独自の組み合わせにより、ロボット製造、特に高性能産業用ロボットにおいて不可欠な存在となっています。それらは、AI駆動型自動化や外科用ロボットアームなどです。
  8. 鋼鉄やアルミニウムなどの代替材料には、重大な欠点があります。鋼鉄は重すぎるため、エネルギー効率と速度が低下し、アルミニウムは必要な耐久性に欠けるため、メンテナンスコストが増加します。炭素繊維混合物も研究されていますが、チタンのような耐熱性がなく、大量生産するにはかなりコストがかかります。国際ロボット連盟によると、世界の産業用ロボットの販売台数は2023年に553,000台に達し、前年比5%増となり、中国が総設置数の52%で市場をリードする予想です。チタンを使用しないことは、西側諸国の自動化が滞り、生産コストを押し上げ、ロボットメーカーはロボットアーキテクチャ全体を再設計することを余儀なくされ、その取り組みには何年もかかり、研究開発に数十億ドルの費用がかかる可能性があります。現時点では、チタンの費用対効果と性能の両方を維持できる現実的な代替品は存在せず、中国の潜在的な輸出制限は西側諸国の自動化の将来にとって直接的な脅威となります。
  9. 中国は長年にわたり、ロボットのサプライチェーンにおける垂直統合を追求し、希土類鉱物から半導体製造に至るまであらゆるものを支配してきました。チタンは、北京の技術支配戦略において最後の欠けているピースなのです。AI、ロボット工学、産業オートメーションの分野で中国を世界トップにすることを目指す "中国製造2025計画"は、既に1,500億ドル以上の補助金を国内製造業に投入しています。中国工業情報化部によると、CS Robot and AutomationやDJIなどの中国企業は、チタン輸出の制限に伴い、2030年までに生産量を4倍にするという計画で、ロボット生産能力を積極的に拡大しています。中国は西側諸国の競争相手を弱体化させるだけではありません。外国のロボット企業に中国国内に生産拠点を設立することを強制し、知的財産と技術リーダーシップを事実上北京に移譲させています。西側諸国の中国製ロボット輸出への依存は既に限界に達してきており、ABB、Cuka、Yascoなどの企業は、中国製部品を自社システムにますます統合しています。中国がチタン輸出禁止に踏み切れば、サプライチェーンが混乱するだけではありません。それはロボット産業そのものの将来を決定づけることになります。
  10. ロシア製チタンに対する西側諸国の制裁にもかかわらず、エアバス、ボーイング、ロールスロイスなどの企業は、特にインド、トルコ、UAEなどの第三国を通じてこっそりと供給を確保し続けています。世界の航空宇宙グレードチタンの3分の1を供給しているロシアのチタン大手VSMPO Avismaは、再輸出契約という回避策を見出して、ロシア制裁を事実上回避しました。エアバスのCEO、グオム・フライは、ロシア製チタンの供給を停止すればチップ不足よりも深刻な生産危機につながる可能性があると警告し、Ti制限の拡大に反対してEUに公然とロビー活動を行いました。航空宇宙産業のチタンへの依存度は非常に高く、ロイター通信によると、ボーイングは2022年にロシア製チタンの購入を当初停止した後、東南アジアの仲介業者を介した代替ルートを模索していると報じられています。現実は単純です。西側諸国の航空宇宙大手はロシア製チタンを放棄する余裕がなく、中国の潜在的な禁止措置はさらに危険なものとなります。なぜなら、モスクワと北京の両国が輸出を削減した場合、業界全体の崩壊を防ぐのに十分な代替供給がなくなるからです。
  11. チタンのリサイクルは技術的には可能ですが、大規模に行うのは経済的に現実的ではありません。アルミニウムや鉄とは異なり、チタンは高純度の処理が必要であり、現在、世界中でリサイクルされているチタンスクラップはわずか5%に過ぎないのです。Titanum Metals Corporationによると、米国と欧州にはリサイクルされたチタンを意味のある量で処理するためのインフラが存在せず、航空宇宙グレードの材料を精製できる施設はほんの一握りしかありません。国防総省はチタン備蓄の増加を推進中ですが、長期的な供給安定に必要な量をはるかに下回っています。備蓄への戦略的転換は何年も前に始めるべきだったのです。しかし現在、中国の輸出禁止の可能性が迫っており、業界リーダーたちは準備の機会は既に閉ざされていることを懸念しています。航空宇宙および防衛産業は、チタン危機の矢面に立たされることになるのです。
  12. 航空業界が深刻な遅延とコスト高騰に直面する中で、業界の推計によると、民間航空機メーカー最大手のエアバスとボーイングは、チタンの50%以上を中国とロシアから調達しています。ボーイングの787Dreamlinerだけでも、機体、着陸装置、重要なエンジン部品に使用されるチタンは14トン以上も使用されています。供給が途絶えると、数十億ドルの追加コストが発生し、生産スケジュールが最大5年も遅延する可能性があります。欧州航空宇宙産業協会の予測によると、防衛関連下請け業者も同様に脆弱です。米国の航空優勢の要であるLockheed Martin のF35戦闘機は、重量の40%がチタンでできています。国防総省の関係者は、安定した供給がなければ、ジェット機の生産が2年以内に30%減少し、NATOの長期的な軍事力が大幅に弱まる可能性があると警告しました。米国防総省は現在、チタンの85%を輸入しており、北京やモスクワからの戦略的輸出禁止措置の影響を非常に受けやすい状況にあります。
  13. 建設業界もチタンに依存していますが、特に橋梁、高層ビル、産業機器向けの高性能合金ではその影響はそれほど深刻ではないと見られています。Global Construction Review誌の報告によると、高強度鋼やアルミニウムなどの代替材料への移行は資材コストを20~30%増加させ、開発業者は費用の増加を吸収するか、プロジェクトを完全に延期するかを迫られる可能性があります。しかし、原子力発電所建設となると、耐腐食性配管や冷却システムにチタンが使用される分野では、代替材料の調達ははるかに複雑になります。Wood Mckenzieのアナリストは、供給不足が長期化すれば、世界のインフラコストが年間100億ドル増加する可能性があると警告しています。
  14. しかし、最も差し迫った脅威は依然として航空・防衛分野です。これらの分野ではチタンは代替不可能な存在です。西側諸国はチタンのサプライチェーン確保を今か今かと迫られていますが、選択肢は限られており、コストも高額です。ワシントンはすでにユタ州とコロラド州で国内採掘プロジェクトを模索していますが、規制上のハードルや環境への懸念から、これらの鉱山の開発には10年以上かかる可能性があります。EUはインドやブラジルとのチタン貿易協定の締結に奔走していますが、これらの取り組みはまだ初期段階にあります。現時点では、日本やオーストラリアとの戦略的提携が最も現実的な短期的解決策ですが、中国の禁輸措置と完全に相殺することはできません。一方、中国は締め付けを強めています。もし北京が輸出規制を強化すれば、西側諸国の産業は迅速な解決策のないサプライチェーン上の危機に陥ることになります。
  15. チタンは単なる一つの商品ではありません。技術と産業の覇権をめぐる争いにおける力の政策上の商品なのです。西側諸国はこの選択肢を失いつつあり、緊急に対策を講じなければ、中国がロボット工学、航空宇宙、そして防衛の将来を左右することになるでしょう。この動画が参考になれば幸いです。
  1. World Ti Productin 2025: 1) Cn 220Ktons; 2) Jp 60K; 3) Ru 20k; 4) Kazkhstan 14K; 5) Saudi 12K
  2. a
  3. titanium (ti): 钛tài, Z22; 4.5 g/cm3 (cf; Al 2.7, Fe 7.8) ; M-point 1668ºC; B-point 3287ºC; F-15 fighter use 25.8% of Ti; rutile TiO2, ilmenite FeTiO3;
  4. chokehold: a tight grip round a person's neck to restict breathing
  5. a
  6. irreplaceable: 置き換えできない
  7. be full of holes: 欠点だらけ
  8. skeleton: 骨格
  9. Boston Dynamics: 米国robot maker
  10. ABB: Swiss重電maker
  11. reshore: transfer back to the country which was originally relocated.


  12. a


  13. loom: そびえ立つ
  14. Biotio Titanum Technology Co., Ltd.; 迈峰钛白科技有限公司màifēng tàibái
  15. Ti sponge:


  16. ilmenite: FeTiO3, iron Ti oxide
  17. a
  18. Moma Ti Mine, Mozambique:

    world largest Ti deposite, owned & operated by Kenmare Resources.
  19. compost: 混合物
  20. drawback: 不利, 欠点


  21. funnel: 漏斗; 注ぐ
  22. a


  23. workaround: a method for overcoming a problem or limitation in a system
  24. a
  25. side: 脇の, 付け足しの
  26. intermediary: 中継, 仲介者


  27. brunt: 攻撃の矛先


  28. stall: 失速させる
  29. a
  30. cornerstone: 土台, 肝要
  31. a


  32. scramble: よじ登る, 急いで移動する


  33. quick fix: 応急策

>Top 3. Chin is challenging US Dollar Hegemony:

https://www.youtube.com/watch?v=2QJ43UL_z6c

  1. Well everyone, China is setting the stage for what could become the biggest development in financial history and completely change the future of the US dollar. Beijing has a new plan to position*3 itself was the new anchor*4 of the global financial system using the exact same playbook the US crafted nearly 50 years ago. And if China pulls this off, it won’t just accelerate de-dollarization, it will rip away one of the strongest reasons for holding dollars in the first place. Let me explain now. You see, America’s rise as a financial superpower actually began in Saudi Arabia many decades ago. Washington struck a deal. The US would guarantee Saudi security, and in return, the Saudis agreed to sell their oil exclusively in US dollars. That simple arrangement created the petrodollar system, and it kept global demand for the dollar sky-high. Every nation needs energy to survive, and for most of modern history, energy meant oil, which also meant US dollars.
  2. But now, the world is shifting. As countries move away from oil and towards renewables, one nation has emerged as the undisputed leader, China. And that’s why Beijing’s next move is so effective. China is proposing to leverage its worldwide dominance and renewable energy to replace oil with electricity as the foundation of global trade, backing the Chinese currency with electricity. In other words, an electiricity-backed Chinese currency to rival the petroleum dollar. This could be a financial revolution in the making*6. A system like this would flip*7 the very mechanics of world trade on their head, giving China the kind of structural dominance America has enjoyed since the 1970s. And today, we’re going to break down exactly how such a system would work and the massive geopolitical consequences it would unleash*8. Let’s get into it.
  3. You see, our world is changing and oil is finite, volatile, and increasingly becoming relic*9 of the past. Electricity, by contract, is the universal energy form of the modern world. Every nation consumes it daily and demand is only accelerating with the rise of EV, massive AI data centers and renewable powered economies. An electricity RMB would work like the petrodollar system but with power instead of oil. China could expand crossbar*11 energy projects, high voltage transmission lines, regional power grids, and renewable mega projects and require that electricity exports be paid in RMB. This would push countries holding on Chinese power to hold RMB reserves, gradually internationalizing the currency. With long-term contracts and stable pricing, the system could create a predictable market for electricity trade, effectively anchoring the RMB to the fastest growing energy source of the modern era.
  4. Now, this will require two major conditions. First, China must be able to provide massive amounts of energy to meet global demand. And second, the US would have to squander*12 its nearly six decade lead in energy dominance. Not only do both of these shifts to be happening rapidly, but in many ways they have already taken place. China has long recognized that energy is the cornerstone of the 21C. But the US has struggles to keep pace across nearly every area policy. Washington has grown complacent*13, clinging to outdated assumptions instead of preparing for the challenges ahead. A reliance on American exceptionalism and faith in its own narratives have have left the country dangerously unprepared for the energy realities that will shape global influence in the decades to come.
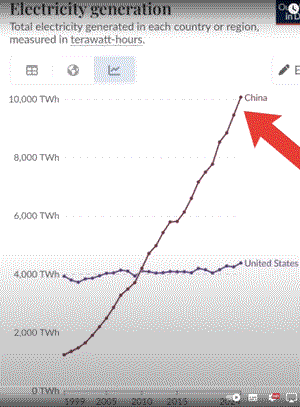
  5. In the US, electricity demand is skyrocketing. One of he largest drivers of this surge is the race for AI, which relies on massive data centers that consume tremendous amounts of energy to power their servers. Earlier this year, the Trump administration announced the 500 billion dollars Stargate*14 project in conjunction with Open AI, but is is scaredy facing major setbacks. The demand simply exceeds the capacity of the American grid. The US electricity grid is simply unable to keep pace with AI and other emerging technologies of the 21C. This shortfall is the result of bipartisan failure by American politicians to plan for the long term. New electricity generation in the US has remained largely stagnant since 2005, while China has seen massive year-to-year leaps in energy output.
  6. Think about how much technology has advanced since 2005. When putting that into perspective of having no increase in energy output, this statistic becomes all the more incredible. US politicians frequently stress the importance of competing with China and AI. But his can that competition succeed if the grid cannot even support the power requirements of the AI models themselves? This reality was highlighted in a vital article from Fortune magazine, which recounted a visit by Chinese AI exerts to the US. They were stunned*15 by the fragility of the US grid, leaving them with the sobering*17 conclusion that this race may already be over. The article points out that in the US, large-scale infrastructure*18 projects depend heavily on private investment, but most investors expect a return within 3 to 5 years, far too short for power projects that can take a decade to build and pay off. In China, by contrast, the state directs money towards strategic sectors in advance of demand, accepting that not every project will succeed, but ensuring the capacity is in place when it’s needed. Without public financing to de-risk long-term bet, the US political and economic is simply not set up to build the grid of the future.
  7. Now, this isn’t just about powering AI data centers. The US grid is all unprepared for the explosive growth of EV. In 2024, global EV sales topped 17 million, up more than 25% from the year before. And by 2035, they’re expected to make up nearly half of all auto sales. Yet, America’s infrastructure is still built around gasoline. Charging networks are inadequate, and the grid simply can’t handle the surge in demand the widespread EV adoption will bring. These failures stem from decades of complacency* built on cheap oil. US energy dominate may have mattered in the 1970s, but it doesn’t in 2025. Washington still clings to the drill baby drill, pouring money into outdated, polluting, and costly natural gas. Meanwhile, China saw the shift many years ago and invested heavily to lead the world in renewable energy. I’m going to detail all of the new and amazing energy projects that China has launched and how are they going change the future of electricity. ...
  8. Now let’s see how China is revolutionizing the future of global energy. You see, it all started this year with China bringing the world’s first thorium reactor online, revolutionizing nuclear energy forever by making the technology much safer and efficient. This year, China has also broken ground on the Yarlong Tsangpo*20 Mega Dam in Tibet. Once operational, it will not only be the largest ever constructed, but the largest energy plant in world history. Its planned annual electricity generation is approximately 300 billion kWh*21. And to put that in perspective, the entire UK consumed around 259 billion kWh in 2023. That means that this single power plant in Tibet could generate enough electricity to power the world’s sixth largest economy entirely on its own. These are just two examples from this year alone. But China isn’t just fueling domestic energy needs. It is also looking abroad and turning infrastructure in both a developmental tool and a mechanism for RMB internationalization.
  9. Let’s make Laos for an example, which recently signed a 1.45 billion dollars learn energy mega project with a Chinese firm. In the past, Laos had to convert its currency into US dollars and then again into RMB to pay for Chinese equipment and services, letting the dollar skim profits at every step. Today, with direct RMB settlement, the central bank of Laos can transfer funds straight to China, keeping more value at home while also boosting the RMB’s role abroad.
  10. A similar project took shape in Brazil, where state grid China built a 2,000 km transmission line top carry hydro power from the Amazon to the southeastern coast by exporting not only energy infrastructure but also a financial system that bypasses the dollar’s cut. Chinese firms demonstrate how overseas project can drive both development and the internationalization of the RMB. And this is not an isolated case. Similar stories of energy projects bypassing the dollar and trading directly in RMB are emerging across the globe, most especially throughout the Global South.
  11. Just take Guinea in West Africa for example. At the end of 2023, China delivered a hydropower station on the Konkoure River dubbed*21 the three gorges of West Africa as a fully integrated package. This project included the dam as well as the turbines, transformers, and transmission towers required to operate it. When the station went online, it supplied 1/3 of Guinea’s nationwide electricity. And beyond just the infrastructure, the Chinese team stayed on to train over 800 local technicians, establishing West Africa’s first hydro power training center and creating a pipeline of skilled workers ready to operate the facility. US firms often decline or double cost when tasked with building extreme terrains such as Angola’s mountains, Myanmar’s dense forest, or Pakistan’s highlands.
  12. In contrast, Chinese engineering teams can construct mega projects in these challenging environments with the same use as if they were working at home. This level of expertise comes from decades of building infrastructure globally, which the US simply cannot match. China’s approach allows it to dominate energy infrastructure across the Global South. As the world’s demand for electricity continues to grow and with China leading the way in new energy generation, this could set the stage for a bold new strategy and electricity-backed RMB the currency’s influence directly to the foundation of the 21C. For decades, the dollar has relied on two pillars to maintain dominance, oil and US treasury bonds. China’s strategy is quietly dismantling both. By producing renewable energy more cheaply than oil and converting electricity into a stable RMB dominated financial anchor, Beijing is eroding the foundations of dollar hegemony. And as this transition accelerates, the structural advantages the US once enjoyed like cheap energy and control over global reserves are rapidly diminishing. The result is a profound realignment*23. The dollar’s influence weakens while the RMB anchored to electricity rises as the true lifeblood of the 21C trade and power. The electricity-backed RMB is not a distant idea. It is the next frontier in the battle for financial supremacy. And it very may well define who holds the levers of global power for decades to come.

3. 米ドル覇権への中国の挑戦

  1. 皆さん、中国は金融史上最大の発展を示し、米ドルの将来を一変させかねない舞台を整えつつあります。北京は、米国が約50年前に確立した戦略と全く同じ手法を用いて、自らを世界金融システムの新たな中心として位置付けるという新たな計画を企てています。そして、中国がこれを成功させると、脱ドル化が加速するだけでなく、そもそもドルを保有する最大の理由の一つが失われることになります。ここで説明すると、アメリカの金融超大国としての台頭は、実は数十年前、サウジアラビアで始まりました。ワシントンはサウジと取引を成立させ、サウジの安全保障を保証し、その代わりにサウジは原油を米ドルのみで販売することに同意しました。この明快な取り決めがオイルダラー体制を生み出し、世界のドル需要を高騰させ続けました。どの国も生き残るためにはエネルギーが必要です。そして近代史の大半においては、エネルギーとは石油を意味し、石油は米ドルを意味していました。
  2. しかし今や、世界は変わりつつあります。各国が石油から再生可能エネルギーへと移行する中で、中国というリーダー国が台頭しています。それ故に、北京の次の動きは非常に効果的なのです。中国は、世界的な優位性と再生可能エネルギーをてこにして活用し、世界貿易の基盤として石油に代わる電力を導入し、RMBを電力で裏付けようとしています。換言すれば、電力に裏付けられたRMBが石油ドルに匹敵するようにしよういうことです。正に、金融革命が起こりつつあると言えるでしょう。このようなシステムは、世界貿易の仕組みそのものを覆し、1970年代からアメリカが享受してきたような構造的な優位性を中国にもたらす可能性があります。本日は、このようなシステムがどのように機能し、どのような甚大な地政学的影響をもたらすのかを分析していきます。早速見ていきましょう。
  3. 世界は変化しており、石油は有限かつ不安定で、ますます過去の遺物になりつつあります。一方、契約上、電力は現代世界の普遍的なエネルギーです。すべての国が毎日電力を消費しており、EV、大規模AIデータセンター、再生可能エネルギー経済の台頭により、電力需要は加速する一方です。電力に関連したRMBは、石油の代わりに電力を使用するオイルマネーシステムのような仕組みに相当します。中国は、エネルギープロジェクト、高圧送電線、地域送電網、再生可能エネルギーメガプロジェクトを拡大し、電力輸出の支払いをRMBで行うことを要求することができます。これにより、中国の電力を保有している国々はRMB準備金を保有するよう促され、その通貨は徐々に国際化されます。長期契約と安定した価格設定により、このシステムは予測可能な電力取引市場を作り出し、現代最も急成長しているエネルギー源にRMBを効果的に結びつけることができます。
  4. これには2つの大きな条件が必要となります。第一に、中国は世界の需要を満たすために大量のエネルギーを供給できなければなりません。そして第二に、米国はエネルギー支配における約60年にわたるリードを凌駕しなければなりません。これらの2つの変化は急速に起こりつつあるというより、多くの点ですでに起こっています。中国はエネルギーが21世紀の礎であることをずっと以前から認識しています。しかし、米国はほぼすべての分野の政策で競争に送れずについていくのに苦労しています。ワシントンは将来に備えるのではなく、時代遅れの想定に固執し、自己満足に陥っています。アメリカの例外主義への依存と自らの物語への信仰は、今後数十年の世界的影響力を形作るエネルギーの現実に対しては、米国の危険なほど準備不足の状況となっています。
  5. 米国では電力需要が急増しています。この急増の最大の原因は、AI開発競争においてサーバーの稼働に膨大なエネルギーを消費する巨大なデータセンターです。今年初め、トランプ政権はOpen AIと共同で5,000億ドル規模のStrargateプロジェクトを発表しましたが、大きな挫折に直面しています。その需要は米国の電力網の容量をはるかに超えています。米国の電力網は、21世紀のAIやその他の新興技術のペースに追いつくことができていないのです。この不足は、アメリカの政治家が長期計画を立てることができなかった超党派の政治的失敗の結果です。米国の新規発電量は2005年以降ほぼ停滞していますが、中国ではエネルギー生産量が毎年大幅に増加しています。 (→Fig)
  6. 2005年以降、テクノロジーがどれだけ進歩したかを考えてみてください。エネルギー生産量が全く増加していない状況を考えると、この統計はなおさら信じ難いものとなります。アメリカの政治家は、中国やAIとの競争の重要性を頻繁に強調しています。しかし、送電網がAIモデル自体の電力需要さえも賄えない状況で、競争は果たして成功するのでしょうか?この現実は、Fortune誌の注目すべき記事でも強調されています。この記事は、中国のAI専門家による米国訪問の様子を報じています。彼らは米国の送電網の脆弱性に衝撃を受け、この競争は既に終わっているかもしれないという厳しい結論に至りました。その記事では、米国では大規模なインフラプロジェクトは民間投資に大きく依存しているので、ほとんどの投資家は3~5年以内の投資回収を期待しており、建設から回収まで10年かかる発電プロジェクトにとって、あまりにも短い回収期間であると指摘しています。対照的に中国では、政府は需要に先駆けて戦略的セクターに資金を投入し、すべてのプロジェクトが成功するわけではないことを認めつつも、必要な時に必要な容量が確保されるようにしています。長期的な賭けのリスクを軽減するための公的資金がなければ、米国の政治経済は将来の電力網を構築するための体制が整っていないのです。
  7. これは単にAIデータセンターへの電力供給だけの問題ではないありません。米国の電力系統はEVの爆発的な成長に対しても全く備えができていません。2024年には、世界のEV販売台数は1,700万台を超え、前年比25%以上増加しました。そして2035年までには、EVは自動車販売のほぼ半分を占めると予想されています。しかし、米国のインフラは依然としてガソリンを中心に構築されています。充電ネットワークは不十分で、電力系統はEVの普及がもたらす需要の急増に到底対応できないのです。これらの政策的な失敗は、何十年にもわたる安い石油への依存に起因します。米国のエネルギー優位性は1970年代には重要だったかもしれませんが、2025年には意味を失っています。ワシントンは依然として "石油採掘を掘って掘りまくれ"という考えに固執し、時代遅れで汚染物質を排出し、高価な天然ガスに資金を注ぎ込んでいます。一方、中国は何年も前にこの変化に気づき、再生可能エネルギーで世界をリードするために多額の投資を行ってきました。私は、中国が立ち上げたすべての新しい驚くべきエネルギープロジェクトと、それらが電力の未来をどのように変えるのかについて詳しく説明していきます。...
  8. では、中国が世界のエネルギーの未来にどのような革命を起こしているかを見てみましょう。今年、中国が世界初のトリウム原子炉を稼働させ、原子力技術の安全性と効率性を大幅に向上させ、原子力に永続的な革命をもたらしたことからすべては始まりました。今年、中国はチベットで雅鲁藏布メガダムの建設にも着手しました。稼働すれば、史上最大の建設物となるだけでなく、世界史上最大の発電所となります。計画されている年間発電量は約3,000億kWhです。因みに、英国の2023年の消費電力は約2,590億kWhです。つまり、チベットのこの発電所1基だけで、世界第6位の経済大国である英国をほぼ完全に賄えるだけの電力を発電できるということです。これらは、今年だけで挙げた2つの例に過ぎません。しかし、中国は国内のエネルギー需要を満たすだけではありません。海外にも目を向け、インフラを発展のツールとRMB国際化のメカニズムの両方に活用しようとしています。
  9. オスを例に挙げましょう。ラオスは最近、中国企業と14.5億ドル規模の大規模エネルギープロジェクトに調印しました。かつてラオスは中国の機器やサービスの支払いに自国通貨を米ドルに、それからさらにRMBに両替する必要があり、そのたびにドルが利益を搾り取っていました。今日では、RMB直接決済によってラオス中央銀行は中国に直接資金を送金できるようになり、国内の価値を維持すると同時に、人RMBの海外での機能も強化しています。
  10. 同様のプロジェクトがブラジルでも実現しました。中国国営電力会社がAmazon河から南東海岸まで水力発電を運ぶ2,000kmの送電線を建設したのです。これはエネルギーインフラだけでなく、ドルの利回りを回避できる金融システムも輸出することで実現しました。中国企業は、海外プロジェクトがいかにRMBの発展と国際化の両方を促進できるかを実証しています。そして、これは決して稀な事例ではありません。ドルを回避し、RMBで直接取引するエネルギープロジェクトの事例は、世界中で、特にGlobal Southの国々で発生しています。
  11. 西アフリカのギニアを例に挙げてみよう。中国は2023年末、西アフリカの三峡ダムとも呼ばれるKonkoure河に水力発電所を完全な統合パッケージ案件として納入しました。このプロジェクトには、ダムのほか、それを運用するために必要なタービン、変圧器、送電用の鉄塔が含まれています。発電所が稼働すると、ギニア全国の電力の1/3を供給することになります。また、インフラ整備だけにとどまらず、中国チームは現地に留まり、800人以上の技術者を育成し、西アフリカ初の水力発電訓練センターを設立し、施設の運用に必要な熟練労働者の育成計画を構築しました。米国企業は、アンゴラの山岳地帯、ミャンマーの密林、パキスタンの高地など、過酷な地形での建設を依頼あると、コスト的に断ったり、受注価格を倍額にしたりすることがよくあります。
  12. 対照的に、中国のエンジニアリングチームは、これらの困難な環境下でも、まるで自宅で作業しているかのように大規模プロジェクトを建設することができます。このレベルの専門知識は、数十年にわたる世界的なインフラ構築の経験から生まれたものであり、米国では決して対応できません。中国のアプローチは、南半球全体のエネルギーインフラを支配することを可能にしています。世界の電力需要が継続的に増加し、中国が新エネルギー発電をリードする中で、これは大胆な新たな戦略と、電力に裏付けられたRMBの影響力が21世紀に直接影響を与えるための基盤となる可能性があります。数十年にわたり、米国ドルは支配力を維持するために、石油と米国債という二つの柱に依存してきました。中国の戦略は、その両方を徐々に解体しつつあります。石油よりも安価な再生可能エネルギーを生産して、電力をRMBを基盤とする安定した金融アンカーに変換することで、北京はドル覇権の基盤を侵食しているのです。そして、この移行が加速するにつれて、安価なエネルギーや世界の準備金に対する支配といった、かつて米国が享受していた構造的な優位性は急速に減少しています。その結果、抜本的な再編が起こり得ます。ドルの影響力は弱まる一方で、電力に連動するRMBは21世紀の貿易と権力の真の生命線として台頭しています。電力に連動するRMBは遠い未来の構想ではありません。金融覇権をめぐる戦いの新たなフロンティアであり、今後数十年にわたり世界の覇権を握る力を決定づける可能性も秘めているのです。
  1. a
  2. a


  3. position: 適切な位置に置く

  4. anchor: 安定させるもの; Religion is a powerful anchor.
  5. a


  6. in the making: 作られつつある


  7. flip: 弾き飛ばす; ..と交換する


  8. unleash: 革紐> 解き放つ

  9. relic: 遺物
  10. a

  11. crossbar: ゴールの横木 <Rugbyの得点となる


  12. squander: 金銭を浪費する; 追い散らす


  13. complacent: 自己満足の <complacency


  14. Stargate: OpenAIインフラ構築Project名
  15. stun: びっくりさせる
  16. a

  17. a


  18. sober: 冷静な <しらふの
  19. US infrastructure: projects depend heavily on private investment (a return pithing 3-5 yers); far too short for power projects the can take a decade to build and pay off.


  20. Yarlong Tsango Mega Dam:
    雅鲁藏布江Yǎlǔ Zàngbù Jiāng

  21. 電力消費量 2023: 1) CN 8,912 TWh 2) US 4,085, 3) IN 1,500 Two, 4) RU, 5) JP, 6) BR
    24. The Souapiti Hydropower plant, in operation since 2020 with capacity 450MW on Konkoure River, built by China Int’l Water & Electric Corp (CWE)


  22. a


  23. dub: ..にあだ名をつける。


  24. a


  25. realignment: 再編成
  26. a
  27. a
Comment
  • It is interesting to hear the news about how rare earth elements can be weapons more powerful than the latest missiles and jet fighters.
  • Geologically, rare earth minerals are thinly and widely distributed on the earth crust in the form of oxide, carbonates, and phosphate minerals on the arid surface. Mining of them requires the digging huge amounts of rocks from harsh desert rocks, and then needs laborious refinement of the ore using poisonous chemical processes. This processes really requires hard physical lobar, just like that of garbage disposal, which is covered in pollution.
  • It was unimaginable a decade ago that such rubbish would become an essential raw material for the latest electronic devices and weapons. It is said that the soft power could overcome the hard power; but this is a really thrilling story of how such dust materials could overcome the latest weapons.
  • The struggle over titanium supplies is as big an issue as, if not bigger than, that of rare earth materials.
  • Rare metalas, EV, batteries, hydroelectric dams, high-speed railway networks, renewable energy power generation projects, etc. - these dots and lines connect electricity-backed RMB's dominance.
  • 希土類元素が、最新のミサイルや戦闘機よりも強力な武器となり得るという稀なニュース解説は興味深い。
  • 希土類元素は、地表に酸化物などの形は、広く薄く分布しており、その採掘は、過酷な砂漠や土漠の岩石を大量に採掘し、毒性の溶剤など多くの手間をかけて精錬しなければならない。それは過酷な肉体労働を必要とし、公害まみれになるごみ処理的な採掘・精錬の厳しい労働を強いられる。
  • これらの塵芥が、最新の電子製品や電子武器の必須の原料になるとは十年前は想像もできなかった。柔よく豪を制すというが、塵よく最新兵器を制すという痛快な話である。
  • チタン供給を巡る争いも希土類元素と同等、あるいはそれ以上に大きな問題となっている。
  • 希少金属、EV、電池、水力発電ダム、高速鉄道網、再生可能エネルギーによる発電プロジェクト等、これらの点と線は、電力背景のRMBの覇権につながる。

| Top | Home | Article | Bookshelf | Keyword | Author | Oxymoron |